What you can still change before December 31
Before you settle in for winter, there are four things worth looking at.
Every fall, someone asks us a version of the same question: is it too late to do anything about this year's taxes?
It's a fair question. Most people think about taxes in March, when the paperwork starts showing up in the mailbox. By March, the answer is almost always yes.
Why that is
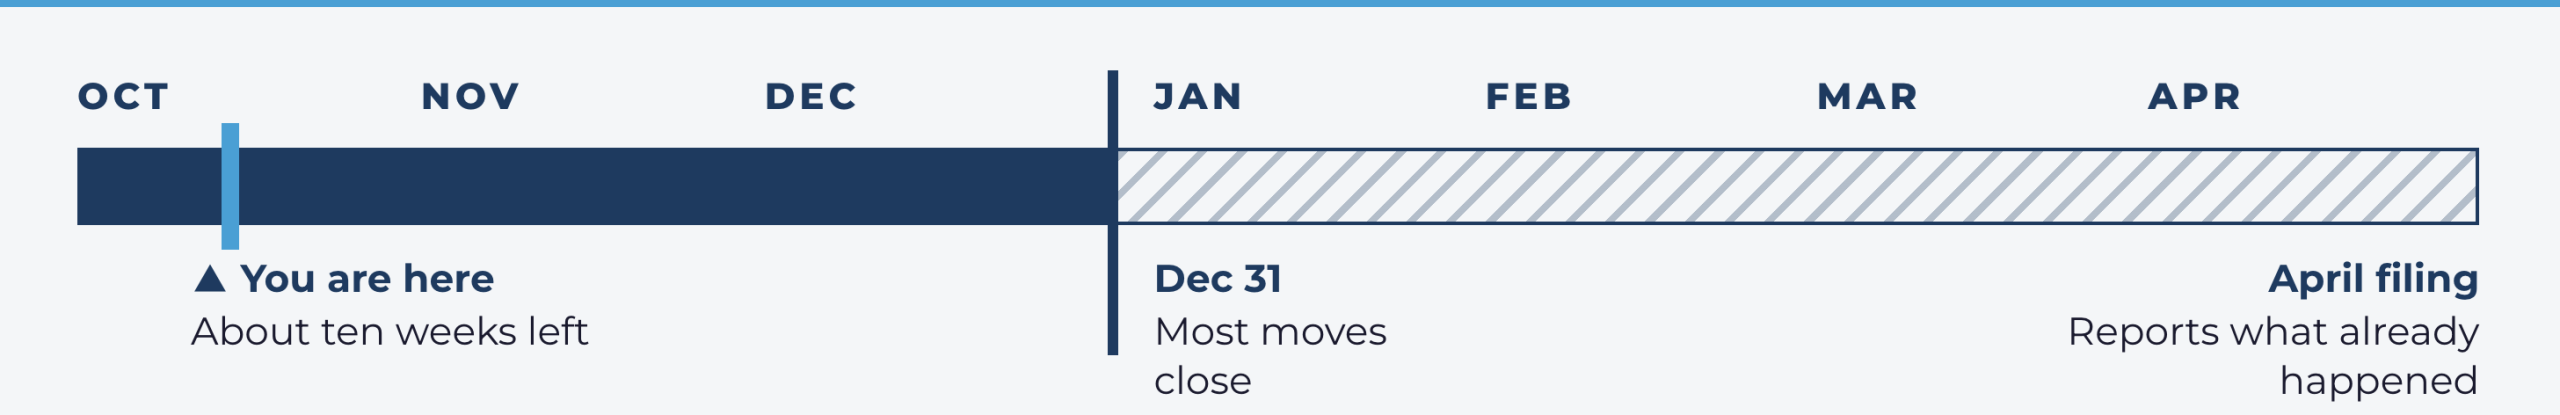
A tax return is a record of something that already happened. Filing it doesn't change the outcome — it reports the outcome. Almost every move that changes what you owe has a deadline of December 31. Your accountant sees your numbers for the first time several weeks after that door has already closed.
Fall is the window. Winter is the receipt.
Four things to check this week
Your withholding
Pull your most recent pay stub or pension statement and look at federal tax withheld so far this year. If you got a raise, changed jobs, or started drawing Social Security, the amount coming out may no longer match what you owe. Correcting it in October spreads the fix across your remaining payments. Correcting it in April just tells you the number.
Your retirement contributions
For 2026 you can put $24,500 into a 401(k), 403(b), or 457 plan. If you're 50 or older, add $8,000 on top of that. If you turn 60, 61, 62, or 63 this year, your catch-up is $11,250 instead of $8,000, as long as your plan offers it — not every plan does.
Payroll deferrals stop at December 31 and don't carry into the new year, so if you want to reach the limit, you have a handful of pay periods left to raise the percentage. One exception worth knowing: starting in 2026, if your wages from that employer topped $150,000 last year, your catch-up has to go in as Roth, which changes the tax math on that piece.
IRA contributions work differently — you have until the April filing deadline, which an extension doesn't move. The 2026 limit there is $7,500, plus $1,100 if you're 50 or older.
Your charitable giving
The rules changed this year. If you don't itemize, you can now deduct up to $1,000 in cash gifts, or $2,000 filing jointly. That one is cash only, and gifts to a donor-advised fund don't count. If you do itemize, only the portion of your giving above 0.5% of your adjusted gross income counts, and whatever that floor cuts is gone rather than carried into next year.
That floor is why bunching is worth a look: two years of giving made in one calendar year can clear it when one year on its own would not. And if you're 70½ or older, a qualified charitable distribution sends up to $111,000 straight from your IRA to a charity. It never enters your income, and it counts toward your required minimum distribution. It has to come from an IRA (not a 401(k)), and it can't go to a donor-advised fund.
Your gains and losses
If you sold an investment at a profit this year, that gain is on the books. If you're also holding something at a loss in a taxable account, selling it before year-end can offset the gain. Losses beyond your gains can reduce ordinary income by up to $3,000 ($1,500 if filing separately), and the rest carries forward.
The catch is the wash sale rule: buy the same investment, or one substantially identical to it, within 30 days before or after the sale, and the loss doesn't count. That includes buying it in your IRA or your spouse buying it.
When it stops being a checklist
None of the four above requires an appointment. You can look at all of them this week.
The reason to sit down with someone is that they affect each other. Raising your 401(k) contribution lowers your taxable income for federal purposes, though it doesn't lower your Social Security or Medicare tax. Lower taxable income can change whether the senior deduction phases out, how much of your Social Security gets taxed, and what your Medicare premium looks like two years from now.
Deciding them one at a time is how people leave money behind.
What that looks like
John and Mary's October check-in
John retired last year. Mary still works part time. In October they looked at three things together:
- 1The withholding on John's pension$1,900 short
- 2Mary's 401(k) percentage
- 3Whether their church giving cleared the new 0.5% floor
Three pension payments adjusted. Nothing else to do.
A check to the U.S. Treasury.
John and Mary are a composite used for illustration, not actual clients.
If nobody has looked at your withholding or your contribution timing since spring, that's a short conversation — and there are about three months left to have it.
Contact Us